
Investment Daily: Global stock markets traded mixed as oil prices extended declines

23 September 2026
Key takeaways
-
US stocks and Treasuries were little changed.
-
European stocks and bond yields edged higher.
-
Asian stocks ended mostly higher.
Markets
US stocks traded mixed on Tuesday, with the S&P 500 ending little changed.
US Treasuries edged lower. 10-year yields rose 1bp to 4.96%.
European stock markets traded mixed but mostly higher on Tuesday amid lower oil prices. The Euro Stoxx 50 was up 0.1%. The German DAX ended flat and the French CAC rose 0.2%. In the UK, the FTSE 100 fell 0.3%.
European government bonds edged lower. 10-year German bund yields ended little changed at 3.46%, and 10-year French bond yields rose 3bp to 4.50%. In the UK, 10-year gilt yields rose 3bp to 5.24%.
Asian stock markets ended modestly higher on Tuesday, as oil prices fell and tech shares pared their earlier gains. Korea’s Kospi was up 0.1%. Hong Kong’s Hang Seng rose 0.2%, while China’s Shanghai Composite edged up 0.1%. Meanwhile, India’s Sensex fell 0.4%.
Crude oil prices extended declines on Tuesday. WTI for November delivery settled 1.2% lower at USD94.6 a barrel.
Key Data Releases and Events
Releases yesterday
The Bank of Japan (BoJ) raised its policy rate by 25bp to 1.00%, as widely expected, and decided to halt the reduction in JGB purchases from April 2027. The BoJ highlighted the risk of underlying CPI inflation deviating upward above 2%.
The Reserve Bank of Australia (RBA) kept its policy rate unchanged at 4.35%, as widely anticipated. Governor Bullock noted upside risks to inflation and did not rule out further tightening.
In China, May activity indicators continued to reflect a two-speed economy. Industrial production showed resilience, up 4.5% YOY, driven mainly by gains in high-tech manufacturing and new energy sectors thanks to robust exports. However, non-tech domestic demand was softer than expected as the property sector remained under pressure. Retail sales fell 0.6% YOY, partly reflecting an unfavourable base effect from last year’s trade-in subsidies. Fixed asset investment contracted by 4.1% YOY in the first five months, despite strong advanced manufacturing investment.
Releases due today (23 September 2026)
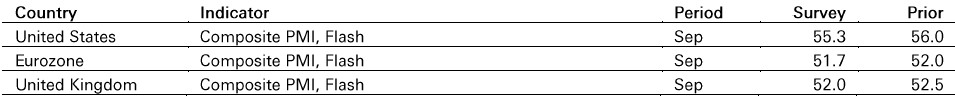
US composite PMI may edge down from its multi-year high, highlighting the resilient US economy. Higher energy prices may lift the prices index.
In the Eurozone, higher energy prices may weigh on the headline index and raise price components of the composite PMI. Employment growth has improved recently.
In the UK, rising energy prices should dampen business confidence and increase price components of the composite PMI. The employment index remains low.


Explore ways to invest
Related Insights


Disclaimer
We’re not trying to sell you any products or services, we’re just sharing information. This information isn’t tailored for you. It’s important you consider a range of factors when making investment decisions, and if you need help, speak to a financial adviser.
As with all investments, historical data shouldn’t be taken as an indication of future performance. We can’t be held responsible for any financial decisions you make because of this information. Investing comes with risks, and there’s a chance you might not get back as much as you put in.
This document provides you with information about markets or economic events. We use publicly available information, which we believe is reliable but we haven’t verified the information so we can’t guarantee its accuracy.
This document belongs to HSBC. You shouldn’t copy, store or share any information in it unless you have written permission from us.
We’ll never share this document in a country where it’s illegal.
This document is prepared by, or on behalf of, HSBC UK Bank Plc, which is owned by HSBC Holdings plc. HSBC’s corporate address is 1 Centenary Square, Birmingham BI IHQ United Kingdom. HSBC UK is governed by the laws of England and Wales. We’re authorised by the Prudential Regulation Authority (PRA) and regulated by the Financial Conduct Authority (FCA) and the PRA. Our firm reference number is 765112 and our company registration number is 9928412.